Uganda and the World Bank have reaffirmed their commitment to accelerating implementation of the US$4.6 billion development portfolio covering 18 operations.
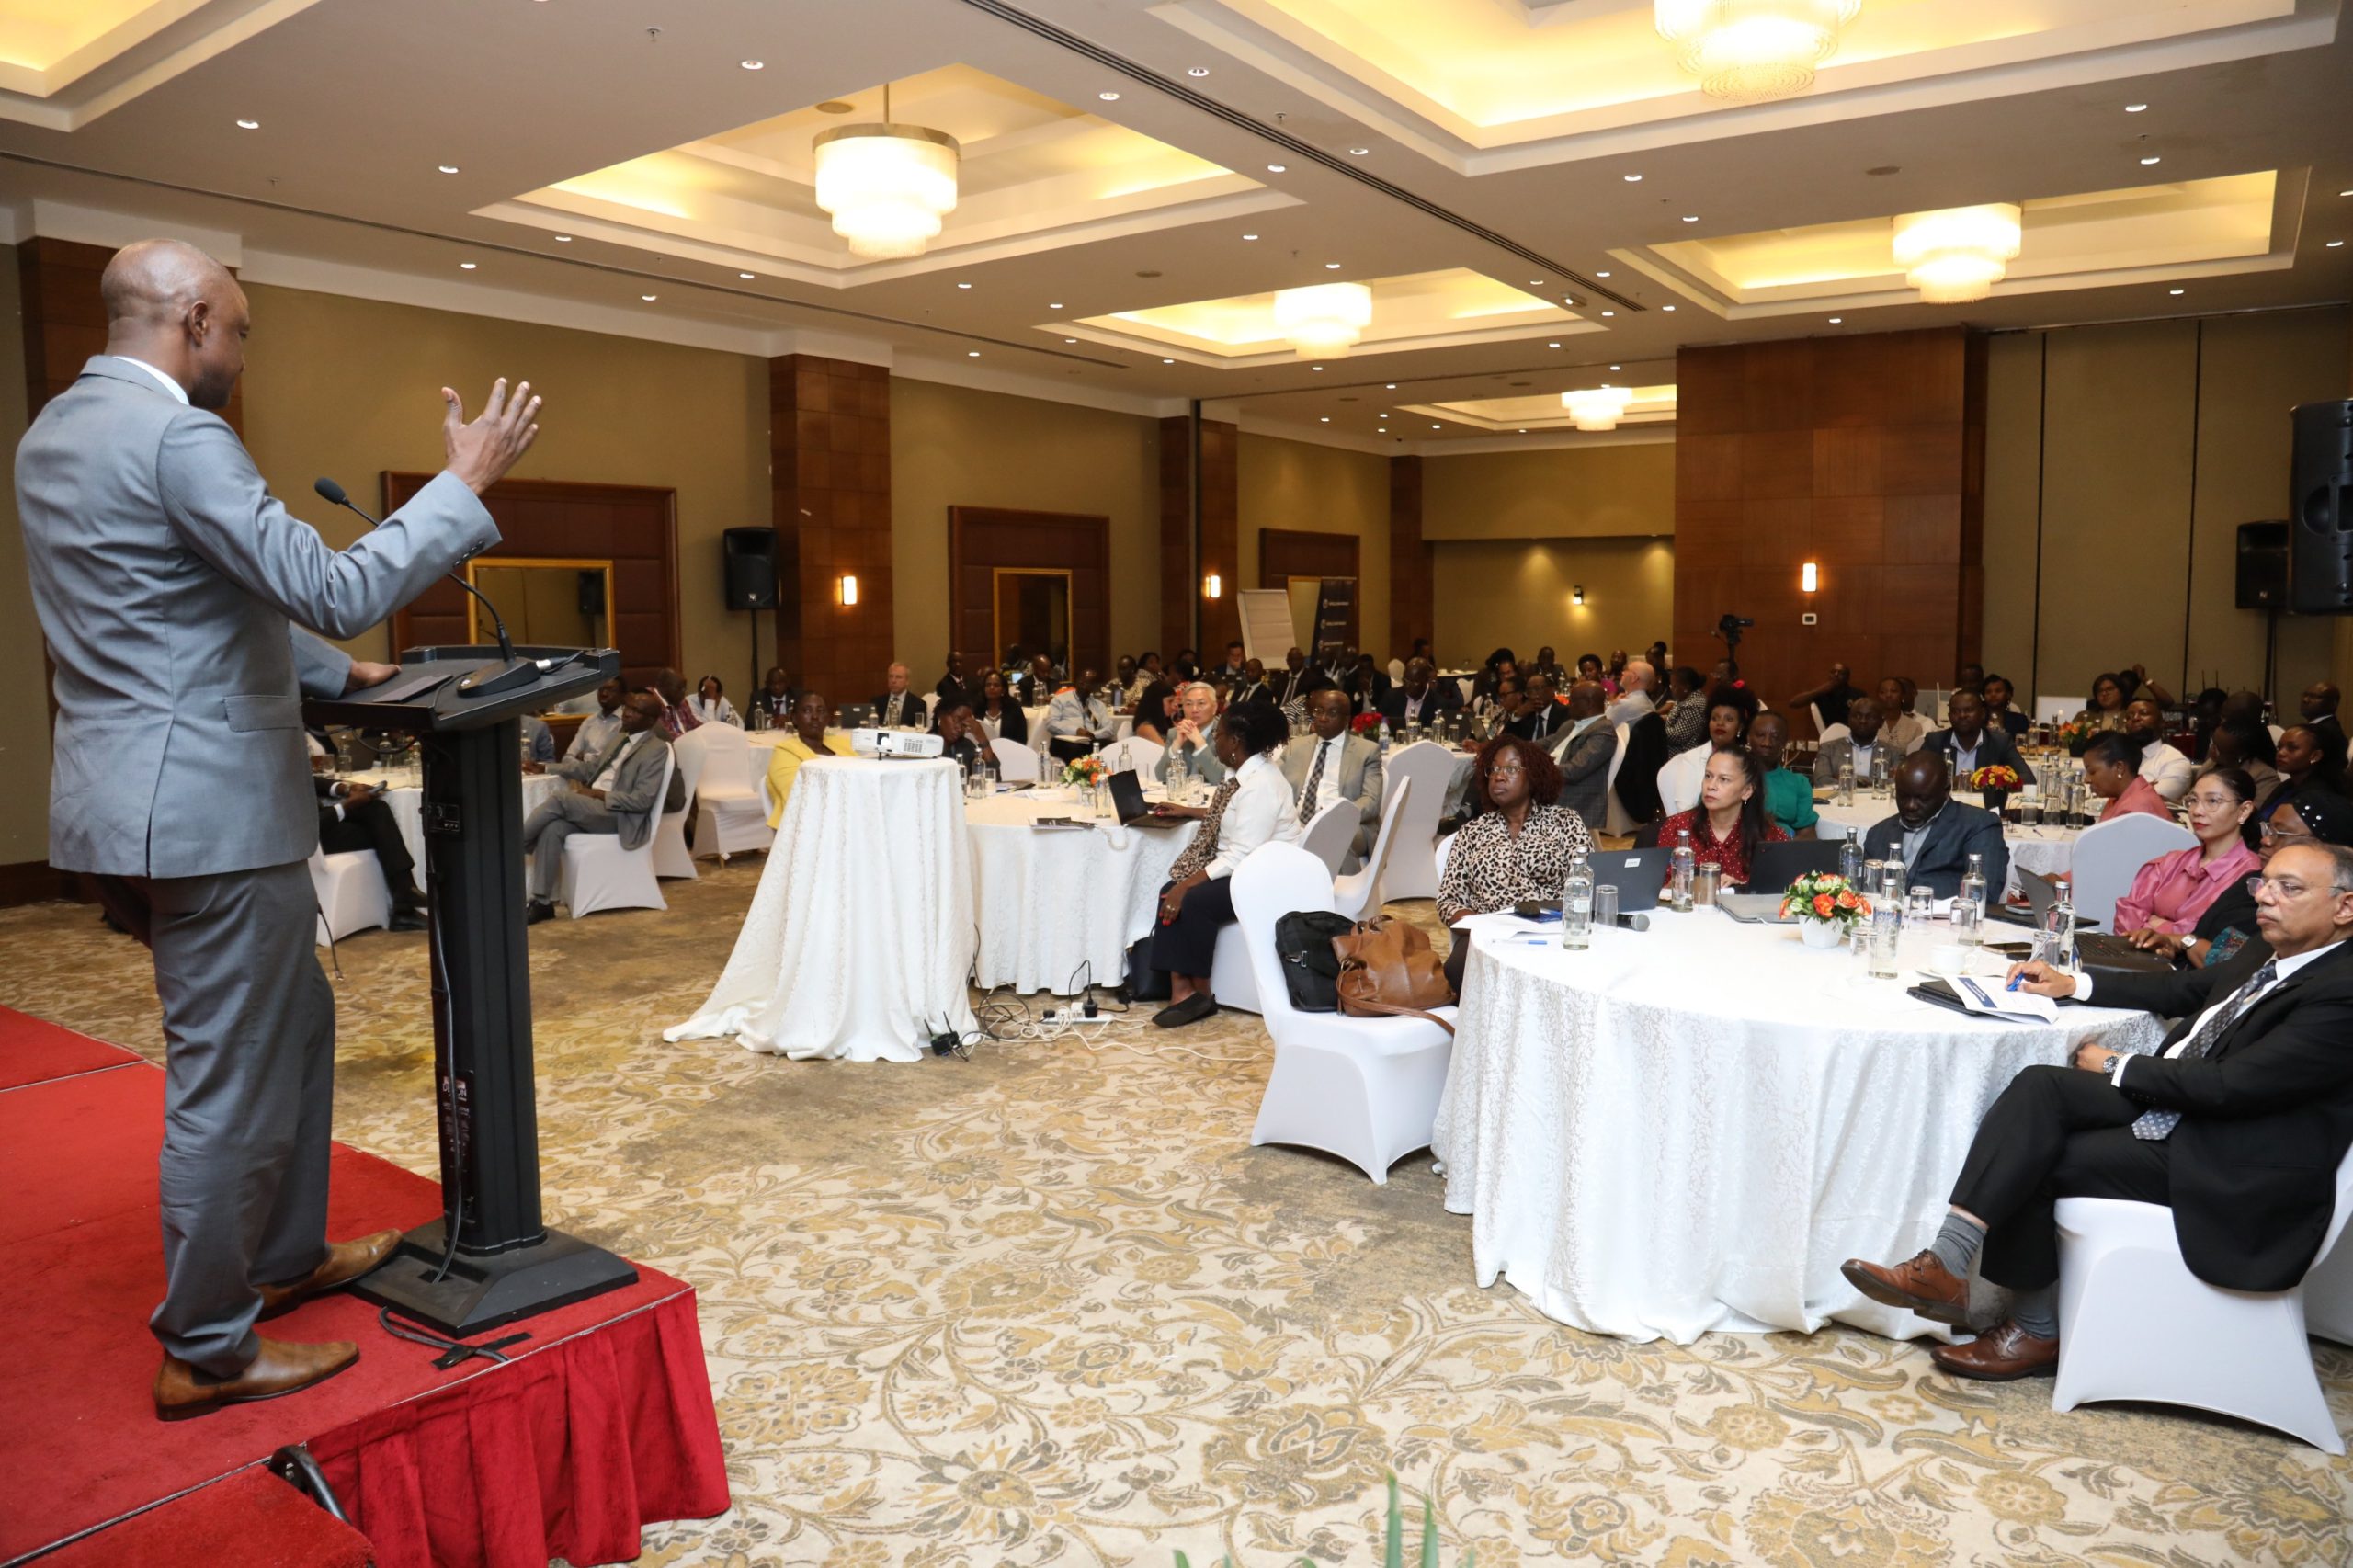
The commitment was made during the Uganda–World Bank Country Portfolio Performance Review, convened at Sheraton Hotel to assess implementation progress, identify delivery bottlenecks and agree on practical, time-bound actions to translate development financing into tangible and sustainable results for Uganda.
Permanent Secretary and Secretary to the Treasury (PSST) Ramathan Ggoobi said Government was undertaking a deeper assessment to distinguish projects delayed by lack of funding from those affected by management-related challenges, including procurement, designs, land acquisition, counterpart funding, approvals and contract management.
“We are going to get quantified answers that separate the fiscal constraint from the management constraint,” he said.
Ggoobi identified the commitment of projects before they are ready for implementation as a major cause of delays. He noted that some projects begin physical works only in their 3rd year, leaving limited time to complete planned activities and increasing the likelihood of extensions, incomplete works and additional costs to Government.
The PSST said Government had strengthened project gatekeeping to ensure that projects meet Public Investment Management System requirements before negotiations, while implementation-readiness conditions must be fulfilled before financing agreements are signed.
The requirements include: approved procurement plans, completed environmental and social safeguards and acquisition of the necessary rights-of-way.
Ggoobi also highlighted electronic government procurement as a key reform for improving efficiency, transparency and accountability. He said all Programme-for-Results operations must use the system, adding that Government will continue engaging the World Bank to bring other projects on board.
With 9 projects scheduled to close in 2027 and 2028, he called for accelerated implementation and timely decisions on projects that cannot be completed within the remaining period. Such projects, he said, should be considered for restructuring, scaling down or cancellation, with extensions reserved for essential ongoing contractual obligations.
He said the review should produce a clear improvement plan for every project, specifying the required action, responsible institution, financing implications & implementation timeline. Persistently underperforming projects would be considered for restructuring or termination.
For the World Bank, Uganda’s development partnership has continued to expand. Qimiao Fan, World Bank Division Director for Uganda, Kenya, Somalia and Rwanda, said the Bank had added almost US$2 billion in new financial commitments to Uganda over the past two years.
He said the portfolio was among the largest International Development Association portfolios in Africa and the second largest in his unit. Approximately US$3.1 billion, equivalent to about five percent of Uganda’s GDP, remains available for disbursement.
Fan described the balance as a significant opportunity to accelerate development, noting that the financing is aligned with Uganda’s Tenfold Growth Strategy, the National Development Plan and the World Bank’s FY2026–FY2035 Country Partnership Framework.
The framework focuses on stronger governance, human capital, connectivity, private-sector productivity and the creation of more and better jobs.
Providing an implementation update, World Bank Senior Operations Officer Tonderai Fadzai Mukonoweshuro said six operations approved in FY2025/2026 had added nearly US$2 billion to the portfolio but had barely started disbursing.